
Our investment approach
How We Evaluate a DST Before We Recommend It
A DST can help complete a 1031 exchange, but completing the exchange is only part of the decision.
At GCA 1031, we approach DST selection from the perspective of a real estate investor. We evaluate the sponsor, the underlying real estate, the financing and assumptions, and how the investment fits within the investor’s broader strategy.
Our objective is to identify investments we believe are worth owning, not simply investments that qualify for a 1031 exchange.
A DST may solve the exchange.The real estate still has to make sense.
Our due diligence process
Looking Beyond the Sponsor Presentation
Every DST comes with an investment story, projections, market information, and offering materials.
Our job is to look beyond the presentation.
Rather than presenting every available offering, we evaluate the broader DST market and narrow the opportunity set based on the factors we believe matter most.
-
Sponsor
Experience, financial strength, operating infrastructure, acquisition discipline, and performance across market cycles.
-
Real Estate
Acquisition pricing, market fundamentals, tenancy, occupancy, cash flow, and potential future value.
-
Structure
Leverage, interest rates, loan maturity, reserves, fees, cost basis, and trust-level terms.
-
Investor Fit
Income objectives, risk tolerance, diversification, debt replacement, investment horizon, and long-term strategy.
Sometimes the most valuable part of due diligence is identifying which investments not to recommend.
Sponsor selection
The Sponsor Is the First Decision, Not the Last
A DST investor does not manage the property, negotiate the financing, approve the budget, or decide when the asset is sold. The sponsor does all of it.
Every projection in an offering is an expression of how the sponsor intends to operate the property.
For that reason, sponsor review comes before we evaluate the real estate itself. An attractive property can be acquired at the wrong basis, financed on the wrong terms, or operated without the infrastructure the business plan requires. We look at the following before an offering moves any further.
-
Track Record Across Market Cycles
How long has the sponsor been operating, and how have prior programs been managed through different interest-rate and real estate environments?
-
Full-Cycle Experience
How many offerings has the sponsor taken through a complete hold and sale, and in which asset classes?
-
Asset Class Specialization
Is this property type a core competency for the sponsor, or a departure from the strategy it is known for?
-
Acquisition Discipline
How does the sponsor source and price acquisitions, and what evidence is there of a willingness to walk away from a deal?
-
Financial Strength
What balance sheet, guarantor capacity, and organizational resources stand behind the offering?
-
Operating Infrastructure
Does the sponsor manage the asset internally or rely on third parties, and how deep are the asset management and accounting teams?
-
Lender and Capital Relationships
Who provides the financing, and what does the quality and durability of those relationships suggest about future refinancing or exit flexibility?
-
Alignment and Fee Structure
How is the sponsor compensated, what related-party arrangements exist, and how are those interests aligned with investors?
-
Reporting and Communication
How frequently and how transparently does the sponsor report to investors, including when a property underperforms the original projections?
If we are not confident in the sponsor, the quality of the property does not change the conclusion.
The real estate
We Underwrite the Property, Not Just the Projected Yield
Projected distributions often receive the most attention when investors compare DSTs. We believe the underlying real estate deserves just as much attention.
A projected distribution is ultimately dependent on the performance of the real estate supporting it.
-
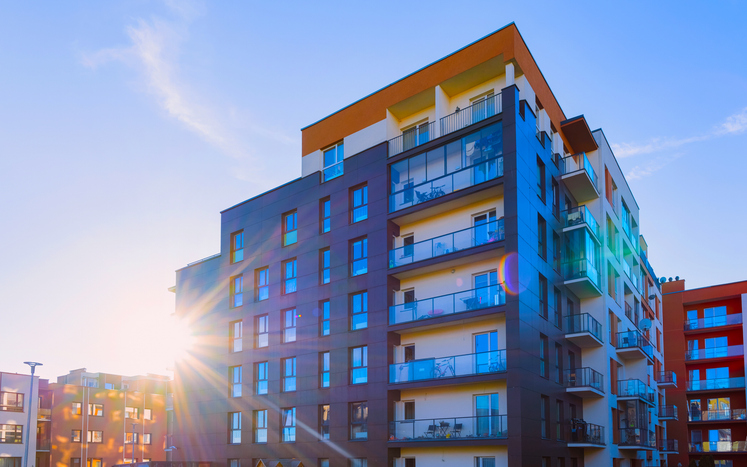
High-Rise -
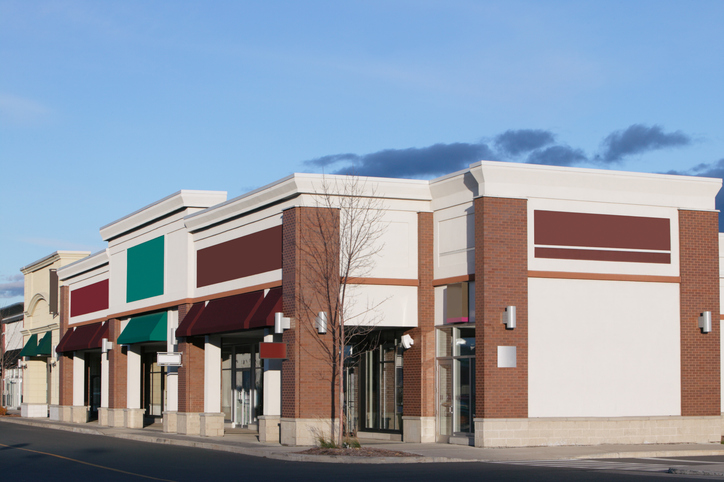
Retail -
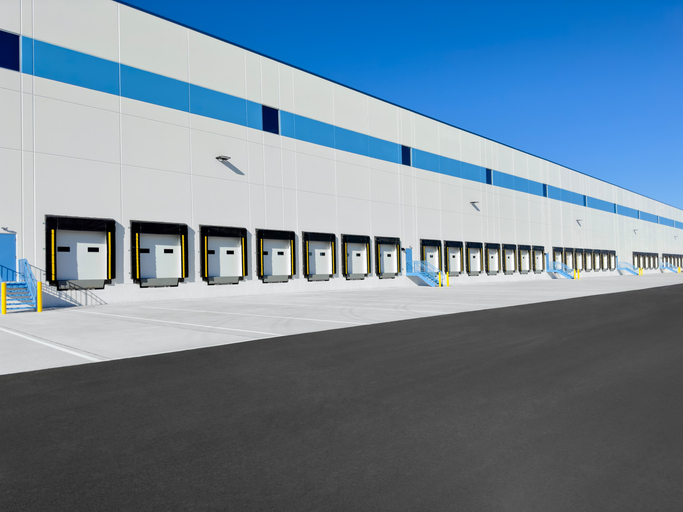
Industrial
Photographs are illustrative of property types only and do not depict a current or prior offering.
-
Acquisition Pricing
Is the purchase price supported by comparable transactions, market capitalization rates, and current market conditions?
-
Market Fundamentals
What do supply, demand, population, employment, competing inventory, and economic trends tell us about the market?
-
Cash Flow
Are projected rents, occupancy, expenses, and distributions supported by reasonable assumptions?
-
Tenant & Occupancy Risk
How durable is the property’s current and future income?
-
Debt Structure
How much leverage exists, and what interest-rate, maturity, or refinancing risks could affect the investment?
-
Reserves
Is sufficient capital available for anticipated and unexpected property needs?
-
Fees & Cost Basis
How much investor equity ultimately goes toward acquiring the real estate versus fees, reserves, financing costs, and other offering expenses?
-
Exit Strategy
What needs to happen with property performance, valuation, debt, and market conditions for investors to achieve a favorable exit?
Cost basis matters
What Are You Actually Paying for the Real Estate?
A DST investor’s capital does not go entirely toward the property’s purchase price. Investor proceeds may also fund reserves, financing expenses, commissions, organizational costs, and other offering expenses.
We evaluate the complete use of proceeds and ask:
What does this property need to accomplish over the investment period for the investor to overcome the initial cost basis and achieve a favorable outcome?
The amount invested and the value of the underlying property are not always the same number.
Our philosophy
Strategy Before Investment
We do not begin with available DST inventory.
We begin with the investor.
Before evaluating individual offerings, we determine what the investor is trying to accomplish with the exchange and what role the replacement investment needs to play.
- 01
Income Needs
How much income is needed and how dependable does that income need to be?
- 02
Risk Tolerance
What level of property, market, leverage, tenant, and investment risk is appropriate?
- 03
Active vs. Passive Ownership
Does the investor want to continue managing real estate or transition toward passive ownership?
- 04
Diversification
Is the investor concentrated by property, geography, tenant, sponsor, or strategy?
- 05
Exchange Requirements
What equity and debt replacement requirements need to be addressed?
- 06
Long-Term Strategy
Could another 1031 exchange, a future 721 strategy, estate and tax planning, or another ownership objective influence today’s decision?
How the decision gets sequenced
- 01Investor Goals
- 021031 Requirements
- 03Investment Strategy
- 04DST Selection
DST selection comes last, not first. There is no single 1031 strategy that is appropriate for every investor.
Portfolio thinking
From One Concentrated Property to a Broader Strategy
Many investors enter a 1031 exchange after selling a property that represents a significant portion of their real estate wealth. Rather than automatically replacing one concentrated asset with another, the exchange may create an opportunity to evaluate diversification. Our case studies show how this has worked in different investor situations.
Before the exchange
- One property · one market · one source of property-level risk
After — potential diversification across
- Properties
- Markets
- Sponsors
- Property Types
- Strategies
Illustrative only. Segment widths are conceptual and do not represent allocation, weighting, or any specific investment.
Diversification does not eliminate risk. The objective is to determine whether each investment serves a purpose within the overall portfolio.
Selectivity matters
We Do Not Believe Every DST Deserves a Recommendation
Access to a large DST inventory is not the same as investment due diligence.
Our role is to review the market, eliminate opportunities that do not meet our investment criteria, and focus the discussion on investments that we believe warrant further consideration.
Reasons we may pass on an investment include:
- Aggressive acquisition pricing
- Weak market fundamentals
- Excessive leverage
- Refinancing or maturity risk
- Aggressive growth assumptions
- Insufficient reserves
- Tenant concentration
- Questionable exit assumptions
- High investor cost basis
- Sponsor or operational concerns
- Poor portfolio fit
- Broader DST Market
- Initial Screening
- Real Estate & Structure Review
- Investor-Specific Analysis
- Smaller Opportunity Set
Our objective is to determine whether a recommendation is warranted, not to build a case for one.
The GCA 1031 approach
Four Questions Guide Every Recommendation
-
01
Sponsor
Is this a sponsor we are comfortable working with?
-
02
Real Estate
Does the property make sense at the current price?
-
03
Structure
Are the debt, fees, reserves, assumptions, and potential exit reasonable?
-
04
Investor
Does the investment make sense for this investor’s objectives and overall strategy?
If an offering does not satisfy each of these four areas, we do not advance it for further consideration.
Our process
Education Before Execution
The 45-day identification period creates urgency, but urgency should not replace due diligence. We want investors to understand the real estate, financing, projected income, risks, and exit strategy before making an investment decision.
Click any question below to read the answer.
What am I investing in?
With a DST, you are purchasing a beneficial interest in a trust that owns a specific property or portfolio of properties. The property’s location, asset class, tenants, financing, and other material details are identified in the Private Placement Memorandum (PPM), an offering document delivered under the SEC’s Regulation D rules. The sponsor and its affiliated property management team are responsible for operating and managing the real estate on behalf of investors.
How is income generated?
Income is generally generated from the property’s rental or lease revenue, less operating expenses and debt service, if applicable. The sponsor underwrites projected income and expenses in advance, and those assumptions can be reviewed in the PPM. As part of our due diligence, we evaluate items such as lease terms, rental assumptions, occupancy, operating expenses, debt service, and other factors that support the projected distributions. We focus on whether the assumptions supporting the projected income appear reasonable, not simply on the stated distribution rate.
How much leverage is involved?
Leverage varies by offering and is disclosed in the PPM. For 1031 investors, leverage may also play a role in replacing debt from the relinquished property. We evaluate the property’s loan-to-value ratio, interest rate, whether the debt is fixed or floating, the loan term, and the maturity date.
We also consider what would need to occur operationally and from a valuation standpoint for the property to support a successful exit at or before the anticipated debt maturity.
What could affect future distributions?
Distributions can be affected by many factors, including, but not limited to, changes in occupancy, tenant performance, rental income, operating expenses, property taxes, insurance costs, repairs, capital expenditures, debt service, interest rates, and broader real estate or economic conditions.
Projected distributions are not guaranteed and may increase, decrease, or be suspended depending on property performance and other circumstances.
What are the major investment risks?
Risks can include, but are not limited to, loss of principal, reductions or suspension of distributions, tenant or occupancy issues, changes in property values, economic downturns, interest rate changes, operating cost increases, leverage, illiquidity, sponsor-related risks, and the inability to sell the property at the anticipated value or within the projected timeframe.
Each offering has its own specific risks, which are described in detail in the PPM and should be reviewed before investing.
Who makes decisions about the property?
DST investors are passive owners and generally do not participate in day-to-day property management or operating decisions. The trustee, sponsor, and designated property management team are responsible for managing the property in accordance with the DST structure and offering documents.
This passive structure is one of the reasons DSTs may appeal to investors who want continued real estate ownership without the responsibilities associated with directly managing a property.
What happens if the property needs additional capital?
DSTs generally cannot make capital calls requiring investors to contribute additional funds after their initial investment. For that reason, the sponsor typically establishes reserves at the beginning of the investment to help address anticipated repairs, capital expenditures, leasing costs, and other property needs.
As part of our due diligence, we evaluate the amount of reserves established for the property and whether they appear reasonable relative to the property’s age, condition, tenant structure, and anticipated capital requirements.
What is the anticipated exit strategy?
The anticipated exit strategy depends on the offering.
A traditional DST generally contemplates the eventual sale of the underlying real estate, at which point investors may receive their proportionate share of the sale proceeds and, if eligible, evaluate another 1031 exchange.
Certain DST strategies are specifically designed with the potential for a future Section 721/UPREIT transaction, in which the property may be contributed to a REIT operating partnership in exchange for operating partnership units.
Traditional DSTs often target holding periods of approximately five to seven years, although the actual hold period can be shorter or longer depending on market conditions, property performance, financing, and sponsor decisions. Some DST offering documents also provide flexibility for a potential future 721 or UPREIT transaction, but investors should not assume a 721 transaction will occur unless it is a defined part of the investment strategy.
What happens when the property is sold?
When a traditional DST property is sold, investors generally receive their proportionate share of the net sale proceeds after the repayment of debt, transaction costs, and other applicable expenses.
Investors may then choose to recognize the applicable tax consequences or, if they meet the requirements of Section 1031, pursue another qualifying 1031 exchange. Because individual tax circumstances vary, investors should work with their qualified intermediary and tax professionals before the sale occurs to evaluate their options.
Our goal is for investors to understand not only what they are investing in, but why.
Closing
A Real Estate Investment First. A 1031 Solution Second.
A 1031 exchange can provide an opportunity to defer taxes and preserve capital for reinvestment, but tax deferral should not replace investment discipline.
When evaluating a DST, we believe investors should ask more than whether the investment will complete the exchange. They should also ask:
“Would I want to own this investment if I were evaluating it purely as real estate?”
That question guides our approach.
Prefer to talk? Call (949) 235-5606.
Related pages
Where to Read More
Each link below opens in a new tab, so this page stays where you left it.
Important Disclosures
This material is for informational purposes only and does not constitute an offer to buy or sell any investment. It is not intended as tax or legal advice. Please consult your legal or tax professional for specific information regarding your individual situation.
There are material risks associated with investing in private placements, Delaware Statutory Trusts (DSTs), and real estate securities, including the potential loss of the entire investment principal, illiquidity, tenant vacancies impacting income and revenue, general and real estate market conditions, lack of operating history, interest rate risks, competition, including the risk of new supply coming to market, and softening rental rates, general risks of owning/operating commercial and multifamily properties, short-term leases associated with multifamily properties, financing risks, potential adverse tax consequences, general economic risks, development risks, long hold periods, and investors should read the PPM carefully before investing, paying special attention to the risk section.
Diversification does not guarantee a profit or protect against loss in a declining market. Past performance is not a guarantee of, and is not indicative of, future results. Any discussion of sponsor experience or track record is not a representation regarding the future performance of any offering.
DST 1031 properties are only available to accredited investors (typically have a $1 million net worth excluding primary residence or $200,000 income individually/$300,000 jointly of the last three years) and accredited entities only. If you are unsure if you are an accredited investor and/or an accredited entity, please verify with your CPA and Attorney.
Securities offered through Concorde Investment Services, LLC (CIS), member FINRA/SIPC. GCA 1031 is independent of CIS. Concorde is headquartered at 3909 Research Park Drive, Suite 200, Ann Arbor, MI 48108. Phone: (248) 824-6710.